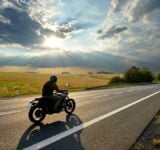
The number of motorbikes fitted with embedded telematics is forecast to more than triple over the next five years, as manufacturers increasingly turn to connectivity to deliver safety, security and connected services.
The number of active OEM telematics systems installed in motorcycles, mopeds and scooters is expected to rise from 19.7 million at the end of 2025 to 62.6 million by 2030, representing a compound annual growth rate (CAGR) of 26%, according to research from IoT analyst firm Berg Insight.
“Important drivers for telematics adoption include safety and security services such as emergency services and stolen vehicle tracking solutions,” said Martin Cederqvist, senior analyst at Berg Insight. “The increasing uptake of electric two-wheelers is also a major factor driving adoption.”
The growth reflects a broader shift among manufacturers towards connected services as a way to differentiate their vehicles and improve the ownership experience. While European manufacturers such as BMW Motorrad have helped establish the market, OEMs in India and China are increasingly driving adoption.
BMW Motorrad introduced emergency call telematics in Europe in 2017, extending the service to North America in 2023. The manufacturer added further connected services in 2024.
In India and China, manufacturers including Ather Energy, Hero MotoCorp, TVS Motor, Bajaj Auto’s Chetak brand, Royal Enfield, NIU Technologies and Yadea are among those offering connected motorbikes. Their services extend beyond emergency assistance and vehicle recovery to features designed to improve the riding experience.
Despite the expansion of factory-fitted systems, aftermarket providers are expected to retain a substantial share of the market, particularly in regions where OEM connectivity is less established.
Berg Insight forecasts that the number of active aftermarket motorbike telematics systems will increase from 13.3 million in 2025 to 23.1 million in 2030, representing a CAGR of 11.7%.
India and China account for the largest installed bases, followed by other Asian markets, Africa, the Middle East and Latin America. Theft prevention and stolen vehicle recovery remain the principal applications for aftermarket solutions.
The supplier landscape reflects the growing convergence between automotive technology and the motorbike market. Established automotive suppliers, including Bosch, Harman International, LG Electronics, Panasonic and Visteon, are applying their existing telematics capabilities to the sector.
Specialist providers are also targeting OEM programmes, particularly in India. These include Ajjas, iTriangle Infotech, Trak N Tell and Vecmocon Technologies. JioThings, part of Jio Platforms, can also combine its telematics offering with cellular connectivity from sister company Reliance Jio Infocomm.
“Suppliers to OEM telematics programmes include Tier 1 automotive suppliers and specialised telematics service providers,” Cederqvist said.
Some manufacturers are also developing elements of their telematics platforms in-house, particularly customer-facing applications and connected services.
In the aftermarket, providers range from established vehicle tracking businesses to companies focused specifically on motorcycles and scooters. European players include GeoRide, Monimoto, Mapit IoT and Scorpion Automotive, while companies such as Ituran and SVR Tracking operate in the Americas. India’s market includes Ajjas, Fleettrack and Onelap Telematics.
There’s plenty of other editorial on our sister site, Electronic Specifier! Or you can always join in the conversation by commenting below or visiting our LinkedIn page.